What Buyers and Sellers Should Know About Mortgage Rates in Billings, MT
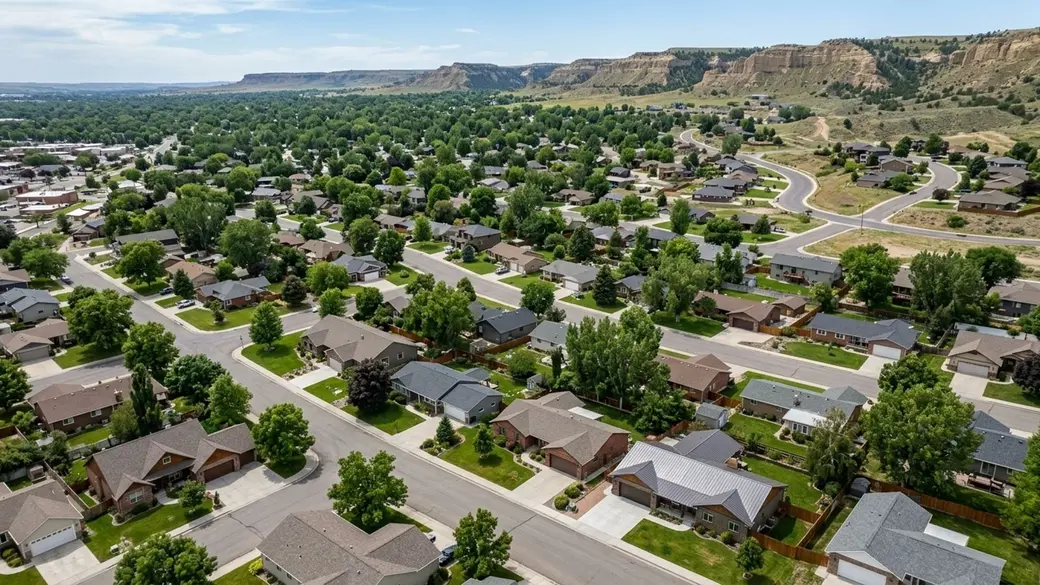
The Billings housing market is sitting at a median sale price of roughly $389,642 right now, with homes spending about 61 days on the market. Whether you're eyeing something near the Rimrocks or trying to move a property in the Heights, your financing cost is going to shape both your timeline and your budget more than almost anything else. These costs dictate what you can afford long before you choose a buyer's agent in Billings, MT to start touring homes.
National headlines love to talk about broad economic shifts, but what matters to you is how those trends land in Yellowstone County. A fraction of a percentage point changes your monthly payment, shifts buyer demand, and determines how long a listing sits in our current inventory of about 671 available homes. That's not abstract - that's your offer, your negotiation, and your bottom line.
Tracking Local Mortgage Rates in Yellowstone County
Mortgage rates move daily - driven by bond markets, inflation data, and broader economic indicators that have nothing to do with what's happening on the ground in Billings. By the time a static number gets published online, it's usually already stale.
If you want to know what you qualify for today, you need a same-day quote or a formal Loan Estimate from a lender. Those documents account for your specific financial profile, the property type you're buying, and the exact time of day the lender prices the loan.
A generalized national average will skew your expectations in ways that can hurt you. Lenders price based on risk, so the rate on your application depends entirely on your individual file - not some statewide figure someone averaged together last week.
How Rate Changes Impact Your Buying Power
The median home price in Billings sits right around $390,000. At that price point, your interest rate determines your real housing cost just as much as the purchase price does.
For illustration only - imagine financing a $390,000 home with a 20% down payment. At an illustrative 6%, the principal and interest payment looks materially different than it does at 7%. One percentage point can add hundreds of dollars a month over the life of a 30-year loan. That's real money, every month, for three decades.
You'll also want to factor in local carrying costs. Yellowstone County's effective property tax rate is approximately 0.82%, which works out to an annual tax bill of around $3,062 on a median-priced home. Add homeowners insurance on top of that, and your total monthly obligation requires careful planning alongside whatever rate you're quoted.
The Price Versus Rate Trade-Off
Buyers ask me all the time whether they should wait for lower rates or negotiate a better price now. With about 3.9 months of supply in this market, you do have some room to negotiate on price - and that can offset a slightly higher borrowing cost.
But waiting for rates to drop carries its own risks. When borrowing costs fall broadly, more buyers come off the sidelines, which drives up competition for that $390,000 median-priced home. You might get a better rate and pay more for the house. It's not always the win it looks like on paper.
Loan Types That Shape Your Monthly Payment
The loan you choose dictates how your interest is calculated and what you write a check for each month. Lenders structure these products differently to fit different financial timelines and down payment situations, so it's worth understanding the basics before you sit down with anyone.
A 30-year fixed loan stretches repayment over three decades - lowest monthly payment, predictable costs. A 15-year fixed comes with higher monthly payments but typically carries a lower rate, and you'll save a substantial amount in total interest over the life of the loan.
Adjustable-Rate Mortgages and Government-Backed Loans
An adjustable-rate mortgage (ARM) gives you a fixed introductory period - often five or seven years - before the rate adjusts annually based on market conditions. If you're confident you'll sell or refinance before that introductory period ends, it's worth a conversation.
Government-backed programs change the math too. FHA loans are built for lower credit scores and smaller down payments. VA loans offer zero-down options for eligible veterans. USDA loans can work well for rural properties just outside the Billings city limits. Each carries its own baseline rate and mortgage insurance structure, so don't assume they're interchangeable.
How to Secure a Favorable Mortgage Rate
Lenders price their best rates for the borrowers who present the least risk. Your credit score is the primary factor in that calculation, and improving it before you apply can make a real difference in your loan terms and monthly payment.
Your down payment matters too. Putting down 20% eliminates private mortgage insurance and often unlocks better pricing. And if you want to go further, you can pay discount points at closing - upfront fees that permanently lower your rate for the duration of the loan.
Shopping Around and Rate Locks
Request Loan Estimates from multiple lenders on the same day. That's the only way to compare them accurately. One bank might offer a lower baseline rate and higher origination fees; another might offer lender credits to offset closing costs. You won't know unless you look at them side by side.
Once you go under contract on a Billings home and find an offer you like, your lender will offer a rate lock - typically 30 to 60 days. That agreement guarantees your quoted terms while the loan moves through underwriting, which means you won't get blindsided by a market move right before closing.
Choosing a Local Mortgage Lender in Yellowstone County
A local Yellowstone County lender is going to understand things a national call center simply won't - Montana property taxes, local appraisal timelines, regional loan programs. That knowledge matters when a transaction gets complicated, and they sometimes do.
You'll run across banks, credit unions, mortgage brokers, and direct lenders when you start shopping. Banks and credit unions lend their own funds and can offer portfolio products. Mortgage brokers shop your application across multiple wholesale lenders to find the best terms. Direct lenders focus exclusively on mortgages and often handle underwriting in-house, which can speed up approvals.
Before you commit to anyone, ask about their average closing timelines and how they communicate outside standard business hours. Real estate happens on evenings and weekends. You want a loan officer who picks up the phone when you need to submit an offer on a Sunday afternoon - because that situation will come up.
What Rate Trends Mean for Billings Sellers
Financing costs don't just affect buyers. They set the pace for the entire Billings market. When borrowing costs rise, some buyers pull back, and that shows up in days on market - which is sitting at roughly 61 days right now.
Price accurately from day one. Buyers in this market are watching their monthly budgets carefully, and overpricing in an environment with 3.9 months of supply means your home sits while other listings move. That's not a position you want to be in.
One option worth considering: a seller concession structured as a credit to buy down the buyer's interest rate. It often costs you less than a full price reduction while giving the buyer meaningful monthly savings. That kind of creative structure can be the thing that gets your listing off the market when the right buyer comes along.
Mortgage Rate FAQs
What are mortgage rates today in Billings, MT?
Mortgage rates change daily based on bond markets and economic data. To get an accurate number for today, you need a customized quote or a Loan Estimate from a local lender based on your specific financial profile.
How much does a 1% difference in mortgage rates cost me on a typical Billings home?
On a median-priced $389,642 Billings home, a 1% rate difference changes the monthly principal and interest payment by hundreds of dollars. Over the life of a 30-year loan, that single percentage point adds up to tens of thousands of dollars in total interest paid.
How do I get the best mortgage rate as a buyer in Billings?
Optimize your credit score, save for a larger down payment, and compare Loan Estimates from multiple lenders on the same day. You can also explore paying upfront discount points to permanently lower your rate.
Should I wait for rates to drop before buying a home in Billings?
It depends on your personal timeline and budget. Waiting for lower borrowing costs can backfire if lower rates bring more buyers into the market, driving up the $389,642 median home price and increasing competition.
How do I choose a mortgage lender in Billings, MT?
Interview local Yellowstone County lenders, credit unions, and mortgage brokers who understand this market. Ask about their communication habits, average closing timelines, and their ability to handle transactions on weekends.
How do current mortgage rates affect my listing price and timeline if I'm selling in Billings?
Higher borrowing costs make buyers more sensitive to pricing, which contributes to the current average of roughly 61 days on the market. Price accurately from the start and consider offering rate buy-down concessions to attract budget-conscious buyers.
Getting Local Real Estate Help in Billings
A real estate transaction takes a solid team. Before you start pulling credit reports or filling out loan applications, it's worth talking to a local agent to map out your strategy first.
An experienced Billings agent can give you a real read on current market conditions and connect you with local lenders who have a track record of closing on time. The right people in your corner make the difference between a smooth transaction and a stressful one - from the first showing to the day you get the keys.
Categories
Recent Posts
Managing Broker & License Partner MT License RRE-BRO-LIC-64264
+1(406) 850-3065 | shawna.morales@engelvoelkers.com